Master Your Money: How to Calculate Net Income the Smart Way
Whether you are trying to qualify for a rental lease, plan your monthly living expenses, or review your company’s fiscal performance, one metric governs every realistic financial move you make: net income.
Many people know their headline salary or total business sales, yet constantly find themselves asking: How do I calculate net income accurately?
Looking strictly at top-line revenue or agreed contractual salary creates a dangerous illusion of cash availability. Knowing how you determine net income—the actual money remaining once taxes, mandatory payroll deductions, or operational costs are subtracted—gives you the only true baseline for sustainable financial planning.
Here is the complete, practical guide breaking down how to compute net income for both personal paychecks and commercial enterprises.
Table of Contents
What Is Net Income? (Gross vs. Net Explained)
Before reviewing how to figure out net income, it helps to clarify the difference between two terms that are frequently confused: gross income and net income.
- Gross Income: The entire amount of money earned before any subtractions take place. For an employee, this is your contractual base salary, hourly rate totals, and overtime. For a business, it represents total revenue or gross billings.
- Net Income: Commonly referred to as “take-home pay” for wage earners or the “bottom line” for commercial entities, net income is what remains after deducting all taxes, contributions, operating expenses, and statutory obligations.
As defined across modern financial frameworks on Investopedia, net income represents your actual spendable, saveable, or investable capital.
1. How to Calculate Net Income for Individuals (Take-Home Pay)
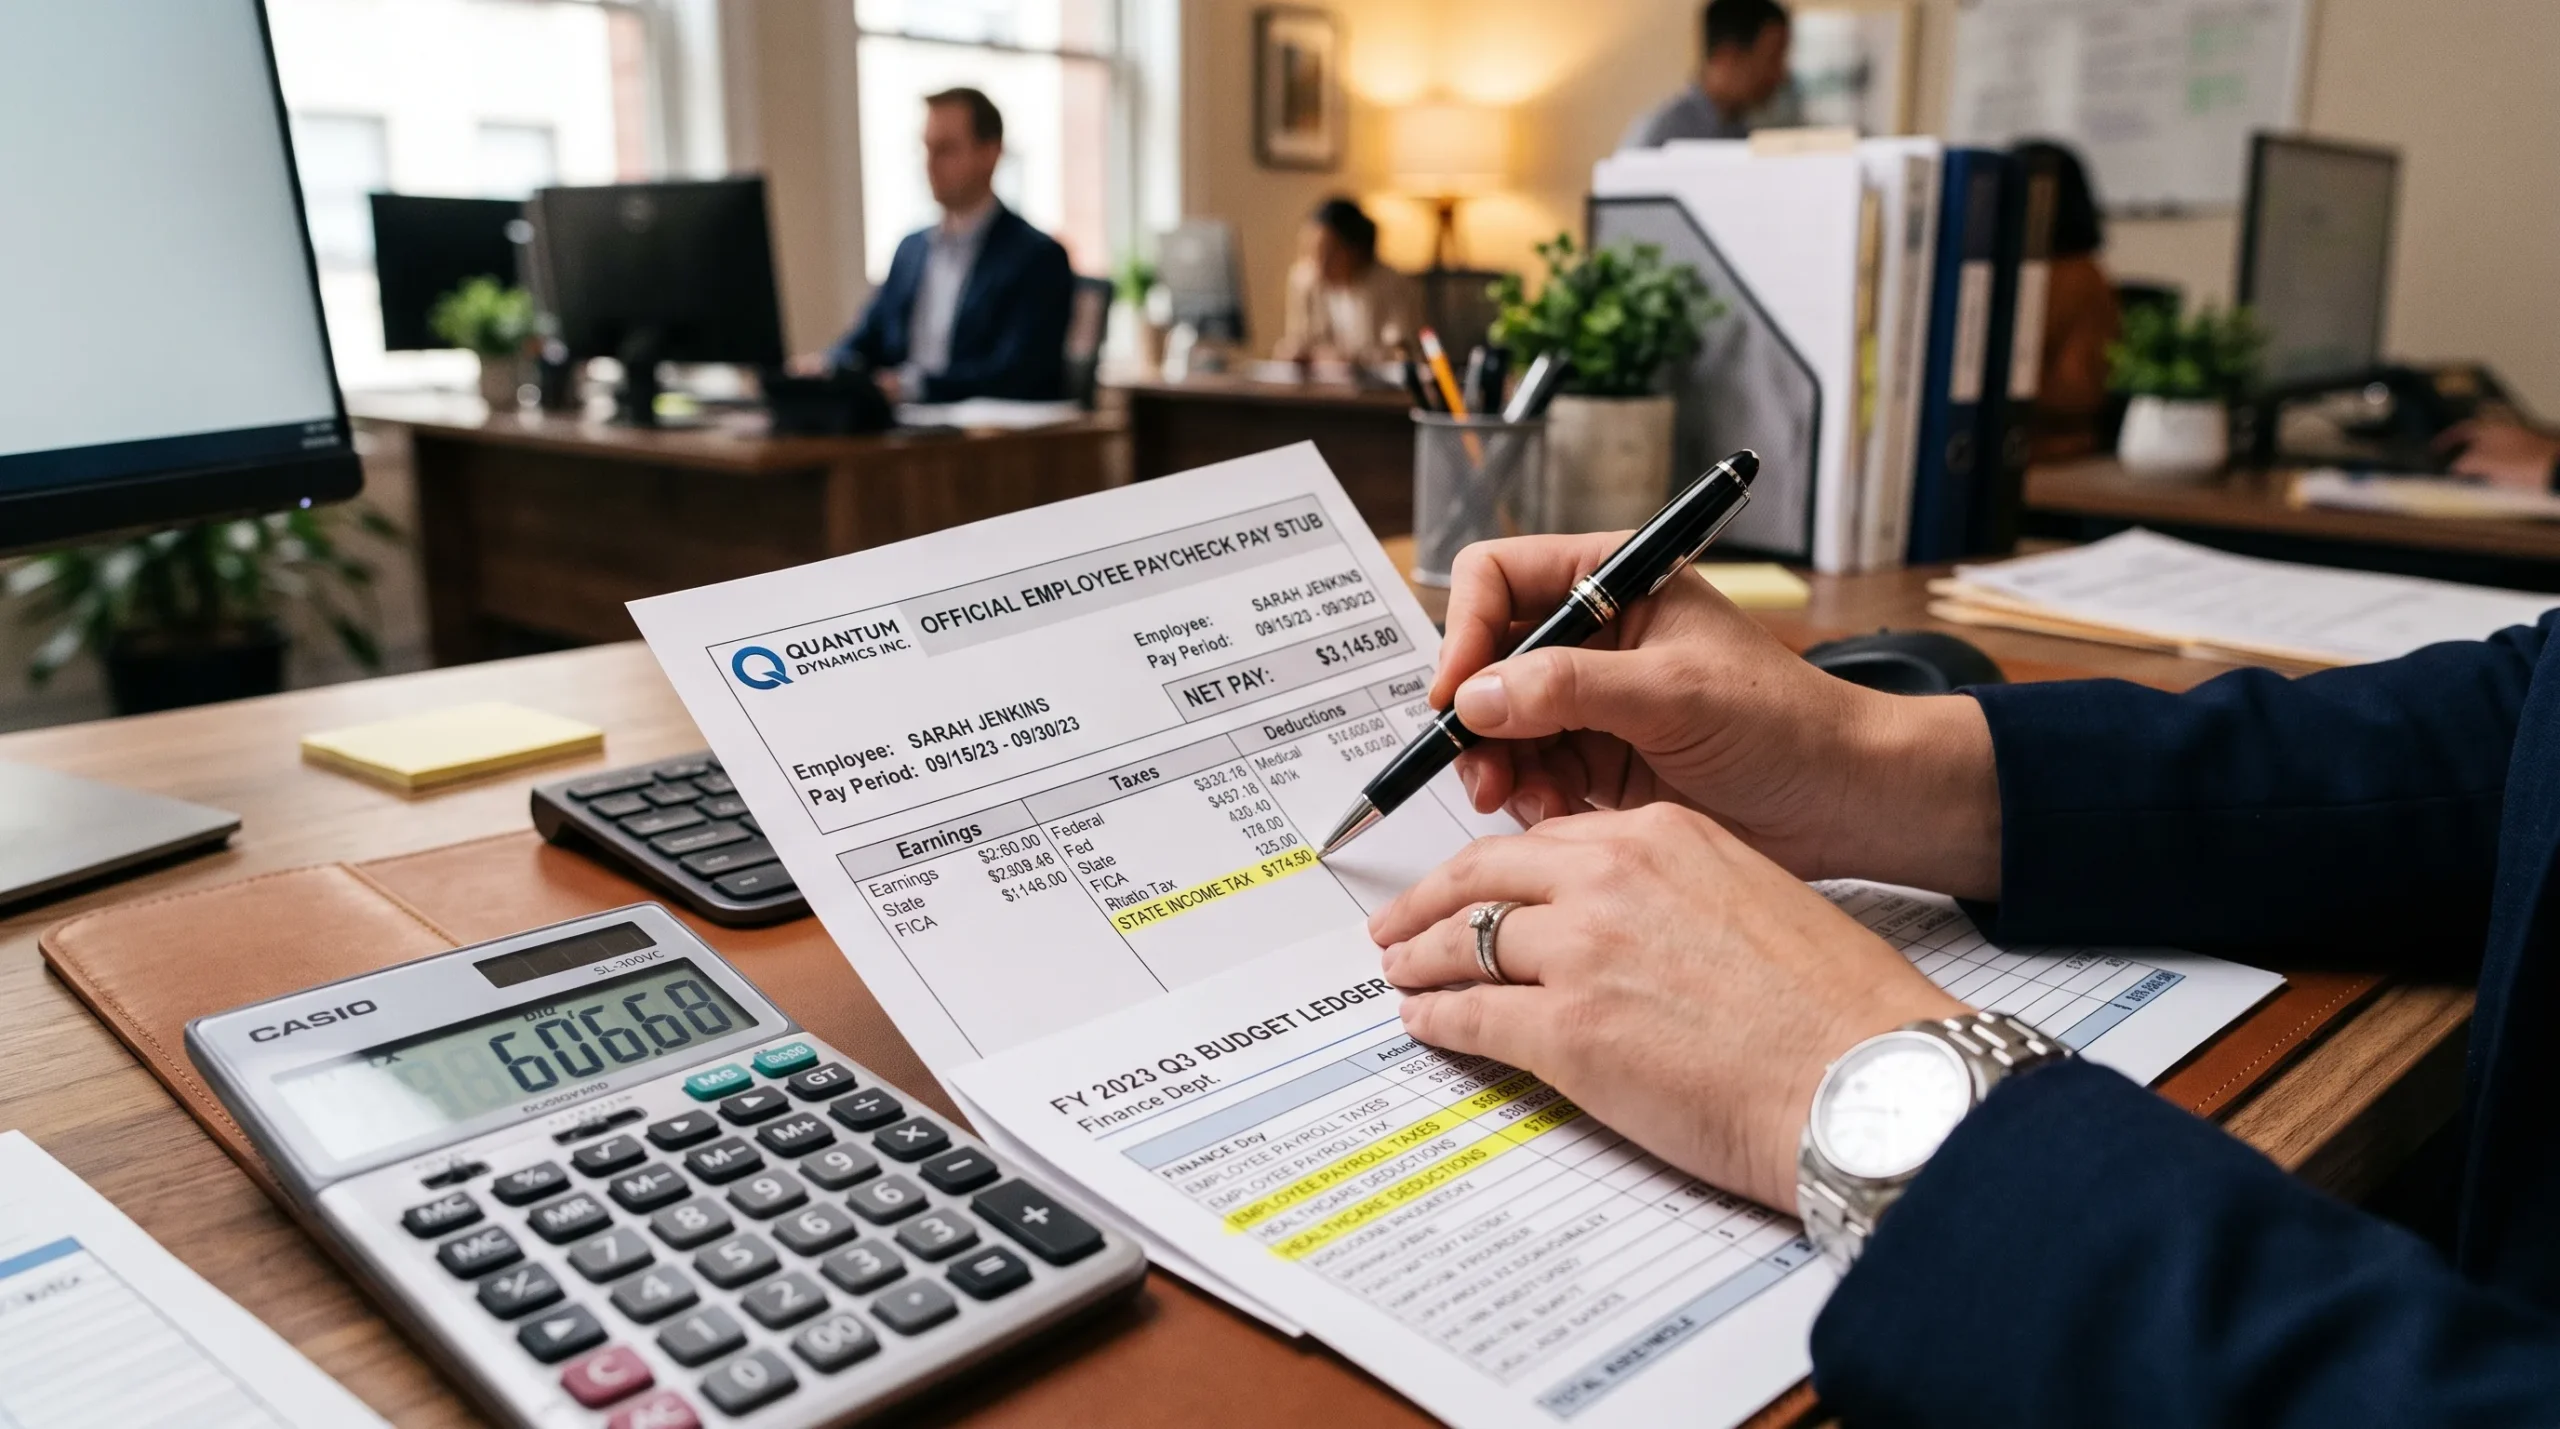
If you are an employee wondering, “How do I figure net income from my paycheck?”, the core calculation follows this fundamental equation:
$$\text{Net Income} = \text{Gross Pay} – \text{Mandatory Taxes} – \text{Payroll Deductions}$$
Personal Net Income Breakdown
| Component | What It Represents | Real-World Examples |
| Gross Pay | Total baseline earnings before any withholdings | Base salary, hourly wages, overtime pay, cash bonuses |
| Mandatory Taxes | Non-negotiable government withholdings | Federal income tax, state/local income tax, and FICA withholdings outlined by the Internal Revenue Service (IRS) |
| Pre-Tax Deductions | Benefit payments withheld before income taxes apply | Traditional 401(k) / retirement plans, HSA/FSA accounts, medical/dental premiums |
| Post-Tax Deductions | Discretionary or required withholdings subtracted after tax | Roth 401(k) contributions, union dues, wage garnishments |
Step-by-Step Personal Paycheck Example
Consider an employee earning an annual base salary of $60,000, paid on a standard monthly schedule ($5,000 gross per month):
- Identify Gross Monthly Pay: $5,000
- Subtract Pre-Tax Benefit Deductions:
- Employer-sponsored health insurance: $250
- Retirement contribution (5% traditional 401k): $250
- Taxable Gross Income remaining: $4,500
- Subtract Income Taxes & Statutory Withholdings:
- Federal & state income tax withholding: ~$550
- FICA taxes (Social Security & Medicare): ~$344
- Calculate Final Net Take-Home Pay:$$\$5,000 – \$250 – \$250 – \$550 – \$344 = \mathbf{\$3,606}$$
While your offer letter states $5,000 per month, your actual discretionary baseline is $3,606.
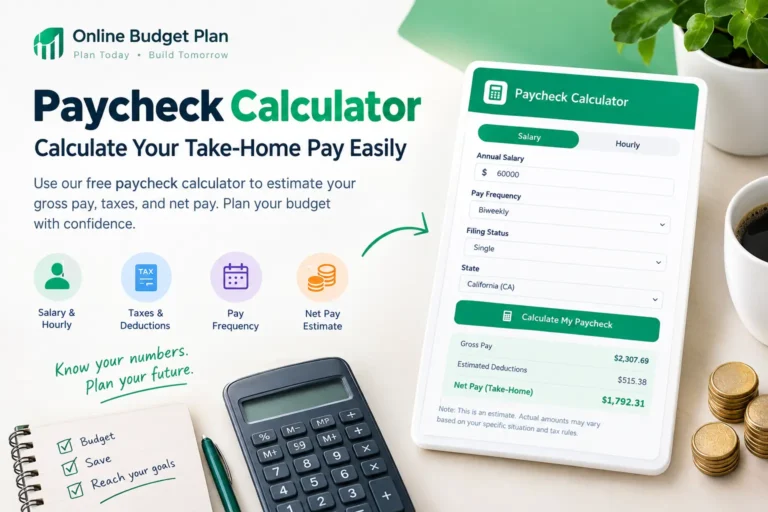
If you prefer to bypass manual formulas across shifting withholding brackets, verify your take-home pay directly with our free Paycheck Calculator.
2. How to Compute Net Income for Businesses (The Bottom Line)
For freelance professionals, sole proprietors, and small business owners asking, “How do you calculate net income for a company?”, the equation requires accounting for cost of goods sold (COGS), operating expenses, interest, and business taxes:
$$\text{Net Business Income} = \text{Total Revenue} – \text{COGS} – \text{Operating Expenses} – \text{Taxes \& Interest}$$
Business Net Earnings Breakdown
| Calculation Layer | Formula | Strategic Meaning |
| Gross Profit | Gross Revenue − Cost of Goods Sold (COGS) | Direct product margin before overhead |
| Operating Income (EBIT) | Gross Profit − Operating Expenses (OpEx) | True operating profitability from everyday activities |
| Net Income / Net Earnings | Operating Income − Interest − Corporate Taxes | The absolute bottom line available for owner distributions or reinvestment |
Small Business Practical Example
A digital service provider or consulting agency records $120,000 in annual gross billings:
- Gross Revenue: $120,000
- Less Direct Project Costs (Hosting, Assets, Contractors): $15,000
- Gross Profit: $105,000
- Less Operating Overhead (Software tools, rent, marketing): $30,000
- Operating Income: $75,000
- Less Loan & Equipment Interest: $3,000
- Less Estimated Income & Self-Employment Taxes: $18,000
- Net Business Profit:$$\$75,000 – \$3,000 – \$18,000 = \mathbf{\$54,000}$$
Mistaking $120,000 in receipts for spendable personal money is the primary reason small business owners face cash crunches. Knowing how you determine net income keeps the business liquid and compliant.
Why Figuring Out Net Income Is Essential for Everyday Financial Decisions
Learning how to get net income accurately is not an abstract math problem—it dictates every component of your personal financial roadmap:
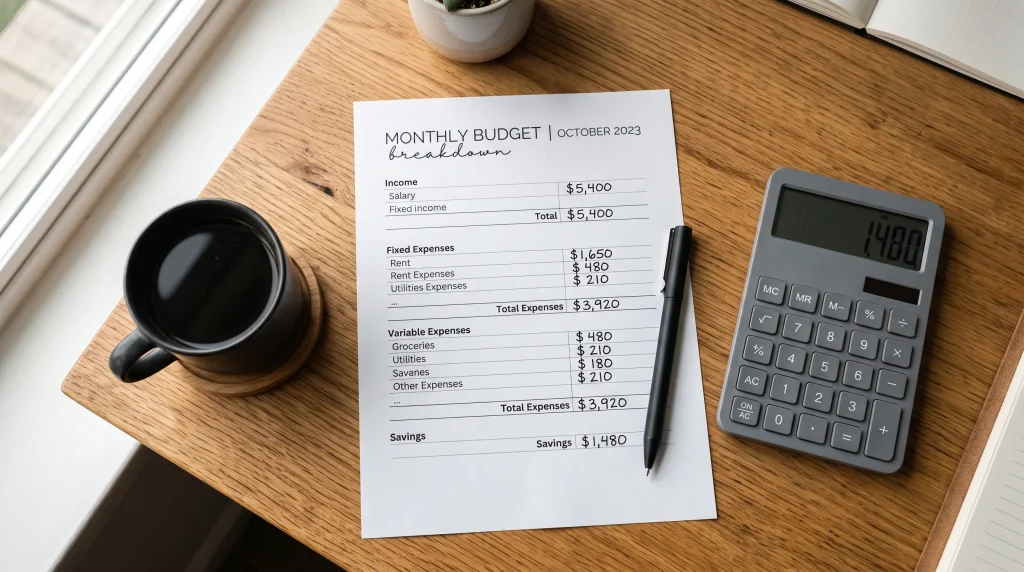
- Building an Accurate Budget: Setting expense limits against gross income leads to immediate deficits. Allocating rent, groceries, and debt payments against real take-home pay preserves liquidity. Once you have established your net total, divide your monthly categories using our Monthly Budget Calculator.
- Plugging Unnoticed Cash Drains: Knowing your exact net ceiling makes overspending glaringly obvious. Pairing your known net pay with regular Free Expense Tracking stops subscription creep and everyday budget leaks.
- Establishing a Realistic Safety Cushion: Conventional guidance from consumer protection agencies like the Consumer Financial Protection Bureau (CFPB) recommends holding 3 to 6 months of baseline living costs in liquid savings. Sizing your reserves around actual net monthly obligations is straightforward using our Emergency Fund Calculator.
- Assessing Mortgage & Debt Affordability: Financial institutions weigh your debt-to-income (DTI) ratios before issuing credit. Before touring properties or refinancing, run your verified net figures through an Online Mortgage Calculator to determine what housing payment fits comfortably within your numbers.
- Accelerating Savings Goals: According to macroeconomic wage trends published by the U.S. Bureau of Labor Statistics (BLS), household savings rates directly depend on discretionary margin rather than raw salary growth. Whether saving for an investment property or a family trip, map out target timelines with our Savings Goal Calculator.
Quick Reference Summary: How Do You Determine Net Income?
To calculate your true take-home pay or net business earnings at a glance, apply this simple sequence:
[Total Gross Earnings / Revenue]
             −
[Mandatory Payroll Deductions / Production Costs]
             −
[Operating Expenses & Benefit Premiums]
             −
[Local, State & Federal Income Taxes]
             =
[Net Income ("Take-Home Pay" or "Bottom-Line Profit")]
Frequently Asked Questions (FAQ)
Does net income include tips, bonuses, and side hustles?
Yes. Any supplemental income earned—including cash tips, freelance checks, quarterly bonuses, or investment dividends—counts as part of your overall gross earnings. Once applicable self-employment and income taxes are deducted from those earnings, the remaining amount is added directly into your net income.
How do you compute net income on an irregular salary?
For commission-based professionals, seasonal workers, or freelancers, compute net income by taking the average net earnings of the previous 6 to 12 months. Alternatively, use the lowest-earning month from the past year as your baseline budget number. Any revenue earned above that baseline should be directed straight into an emergency buffer or tax savings account.
What is the fastest way to increase net income?
Net earnings grow through two distinct levers: increasing gross intake (career development, side businesses, pricing adjustments) or reducing mandatory outflows (canceling non-essential recurring subscriptions, shopping competitive insurance rates, and utilizing pre-tax accounts such as traditional 401ks or HSAs to lower your taxable baseline).
Final Takeaway
Calculating your net income is the single most important step in taking control of your financial life. While gross income shows earning potential, net income defines what you can actually spend, save, and invest today.
Once you know your true take-home pay, eliminate the guesswork: use an accurate budgeting framework, automate savings before spending on non-essentials, and track progress consistently using our free online calculators to build lasting financial independence.